Loading calculator…

Calculate your full monthly mortgage payment - principal & interest, taxes, insurance, PMI, HOA with amortization, PMI drop-off, biweekly comparison, and extra-payment scenarios.
Refreshed daily from Freddie Mac PMMS (weekly survey) · data as of October 15, 2026
Updated monthly from Bank of England (IADB) · latest data September 30, 2026
Updated monthly from ECB Data Portal · latest data August 2026
Updated monthly from Reserve Bank of Australia (F5/F1.1) · latest data September 30, 2026
Reference figure (hand-reviewed June 2026) — not auto-fetched
Rates shown are national averages for reference only. Actual rates vary by lender, credit score, and LTV. US 30/15-yr figures come from the Freddie Mac PMMS public dataset. UK (Bank of England), Euro area (ECB) and Australia (RBA) figures come from official statistics that publish monthly, so they lag by several weeks; each card shows its own latest period. If a source can't be reached, the card keeps the last figures it fetched successfully. Canada is a reference figure only. Countries without one credible national benchmark (e.g. India, where lender rates span roughly 7%–12%+) are intentionally not shown.
| Year | Principal | Interest | Extra | Escrow | Ending balance |
|---|---|---|---|---|---|
| 2026 | $979.73 | $5,853.70 | $0.00 | $1,196.25 | $359,020.27 |
| 2027 | $4,081.90 | $23,251.85 | $0.00 | $4,812.68 | $354,938.36 |
| 2028 | $4,355.71 | $22,978.05 | $0.00 | $4,924.04 | $350,582.66 |
| 2029 | $4,647.88 | $22,685.88 | $0.00 | $5,038.09 | $345,934.78 |
| 2030 | $4,959.65 | $22,374.10 | $0.00 | $5,154.88 | $340,975.12 |
| 2031 | $5,292.33 | $22,041.42 | $0.00 | $5,274.49 | $335,682.79 |
| 2032 | $5,647.33 | $21,686.42 | $0.00 | $5,396.99 | $330,035.46 |
| 2033 | $6,026.14 | $21,307.61 | $0.00 | $5,522.45 | $324,009.31 |
| 2034 | $6,430.37 | $20,903.39 | $0.00 | $5,650.95 | $317,578.95 |
| 2035 | $6,861.70 | $20,472.05 | $0.00 | $5,782.55 | $310,717.25 |
| 2036 | $7,321.97 | $20,011.78 | $0.00 | $5,917.35 | $303,395.27 |
| 2037 | $7,813.11 | $19,520.64 | $0.00 | $6,055.41 | $295,582.16 |
| 2038 | $8,337.20 | $18,996.55 | $0.00 | $6,196.83 | $287,244.96 |
| 2039 | $8,896.44 | $18,437.31 | $0.00 | $6,341.69 | $278,348.51 |
| 2040 | $9,493.20 | $17,840.56 | $0.00 | $6,490.07 | $268,855.31 |
| 2041 | $10,129.98 | $17,203.77 | $0.00 | $6,642.06 | $258,725.33 |
| 2042 | $10,809.48 | $16,524.27 | $0.00 | $6,797.76 | $247,915.84 |
| 2043 | $11,534.56 | $15,799.19 | $0.00 | $6,957.26 | $236,381.28 |
| 2044 | $12,308.28 | $15,025.48 | $0.00 | $7,120.66 | $224,073.00 |
| 2045 | $13,133.89 | $14,199.86 | $0.00 | $7,288.05 | $210,939.11 |
| 2046 | $14,014.89 | $13,318.87 | $0.00 | $7,459.54 | $196,924.23 |
| 2047 | $14,954.98 | $12,378.78 | $0.00 | $7,635.23 | $181,969.25 |
| 2048 | $15,958.13 | $11,375.63 | $0.00 | $7,815.23 | $166,011.12 |
| 2049 | $17,028.57 | $10,305.19 | $0.00 | $7,999.65 | $148,982.56 |
| 2050 | $18,170.81 | $9,162.95 | $0.00 | $8,188.60 | $130,811.75 |
| 2051 | $19,389.67 | $7,944.09 | $0.00 | $8,382.20 | $111,422.08 |
| 2052 | $20,690.29 | $6,643.47 | $0.00 | $8,580.56 | $90,731.79 |
| 2053 | $22,078.15 | $5,255.60 | $0.00 | $8,783.81 | $68,653.64 |
| 2054 | $23,559.11 | $3,774.65 | $0.00 | $8,992.08 | $45,094.53 |
| 2055 | $25,139.41 | $2,194.35 | $0.00 | $9,205.49 | $19,955.13 |
| 2056 | $19,955.13 | $545.19 | $0.00 | $7,026.37 | $0.00 |
Our Mortgage Payment Calculator shows what you'll actually pay each month for a home, not just principal and interest. It works as a full mortgage calculator with taxes and insurance, PMI, and HOA dues built in, so you see your complete PITI payment. Then it shows your payoff date, total interest, home equity, and a full amortization schedule.
Most buyers ask the same things. What's the payment on a $300,000 or $400,000 mortgage? How much house can I afford? When does PMI drop off? Does paying extra really help? This page answers each one with real numbers, whether you call it a mortgage calculator, a house payment calculator, or a home loan calculator.
Need a different angle? The Mortgage Affordability Calculator finds a price your income supports. The Extra Mortgage Payment Calculator tests a faster payoff, and the Amortization Schedule Calculator breaks down every month. You'll find every tool in Mortgage Calculators.
A mortgage payment calculator is a tool that estimates your monthly home loan payment from the home price, down payment, interest rate, and loan term. Calcavio's version also adds property tax, homeowners insurance, PMI, and HOA dues. As a result, you see the full amount due each month, plus total interest over the life of the loan.
Lenders call the full payment PITI: Principal, interest, taxes, and insurance. PMI and HOA dues, when they apply, sit on top of PITI.
That gap matters. Lenders quote principal and interest, but your bank account pays everything. Here's how this calculator compares with a basic payment tool:
| Feature | Basic calculator | Calcavio Mortgage Payment Calculator |
|---|---|---|
| Principal and interest | ✅ | ✅ |
| Property tax by US state | ❌ | ✅ Auto-filled, editable |
| PMI with automatic drop-off | ❌ | ✅ 78% or 80% rule |
| Yearly tax, insurance, and HOA increases | ❌ | ✅ |
| Extra monthly and yearly lump-sum payments | Rarely | ✅ |
| Biweekly savings comparison | ❌ | ✅ |
| Home equity and appreciation chart | ❌ | ✅ |
| Live rate cards (US, UK, Euro area, Australia, Canada) | ❌ | ✅ |
The Consumer Financial Protection Bureau defines the total payment as principal + interest + mortgage insurance + escrow. Here's what each input does:
| Inputs | What each input does? |
|---|---|
| Home price and down payment | The loan amount is the price minus your down payment, entered in dollars or percent. Both fields stay in sync |
| Loan term | A 15-year term raises the payment but slashes total interest compared with 30 years |
| Interest rate | Your quoted note rate, not the APR. Tap "Use" on a live rate card to load today's average |
| Start month and year | These set your payoff date and the yearly schedule |
| Property tax | Pick your state to auto-fill an average rate (California is 0.73%), or type your actual bill |
| Homeowners insurance | Your yearly premium, divided by 12 |
| HOA and other monthly costs | Condo or community dues, plus anything else you want to budget, like a home warranty |
| PMI | Usually required under 20% down. It's charged yearly as a percent of the original loan and ends at 78% (automatic) or 80% (by request) of the original home value |
| Annual increases | By default, taxes rise 2% a year while insurance and HOA rise 3% |
| Extra payments | Extra monthly principal or a yearly lump sum in the month you choose |
| Home appreciation | The yearly growth rate used for the equity chart (3% by default) |
For example, a $450,000 California home with 20% down at 6.51% for 30 years shows $2,676.56 a month and payoff in August 2056.
Principal and interest follow the standard amortizing-loan formula:
M = P × [r(1 + r)^n] ÷ [(1 + r)^n − 1]

- M = monthly principal and interest
- P = loan amount
- r = monthly rate (annual rate ÷ 12)
- n = number of payments (years × 12)
Here's the default scenario solved: $450,000 home, $90,000 down, 6.51%, 30 years.
1. P = $360,000; r = 0.0651 ÷ 12 = 0.005425; n = 360
2. (1.005425)^360 = 7.012691
3. M = 360,000 × 0.005425 × 7.012691 ÷ 6.012691
4. M = 13,695.79 ÷ 6.012691 = **$2,277.81**
Then add escrow: $3,285 yearly tax ÷ 12 = $273.75, plus $1,500 insurance ÷ 12 = $125. The total comes to $2,676.56, and lifetime interest reaches $460,012.66.
PMI follows a simpler formula: monthly PMI = original loan × PMI rate ÷ 12. On a $304,000 loan at 0.55%, that's $139.33 a month.
Early payments are mostly interest. Each month, interest is charged on the remaining balance, so the split shifts toward principal only as the balance shrinks.
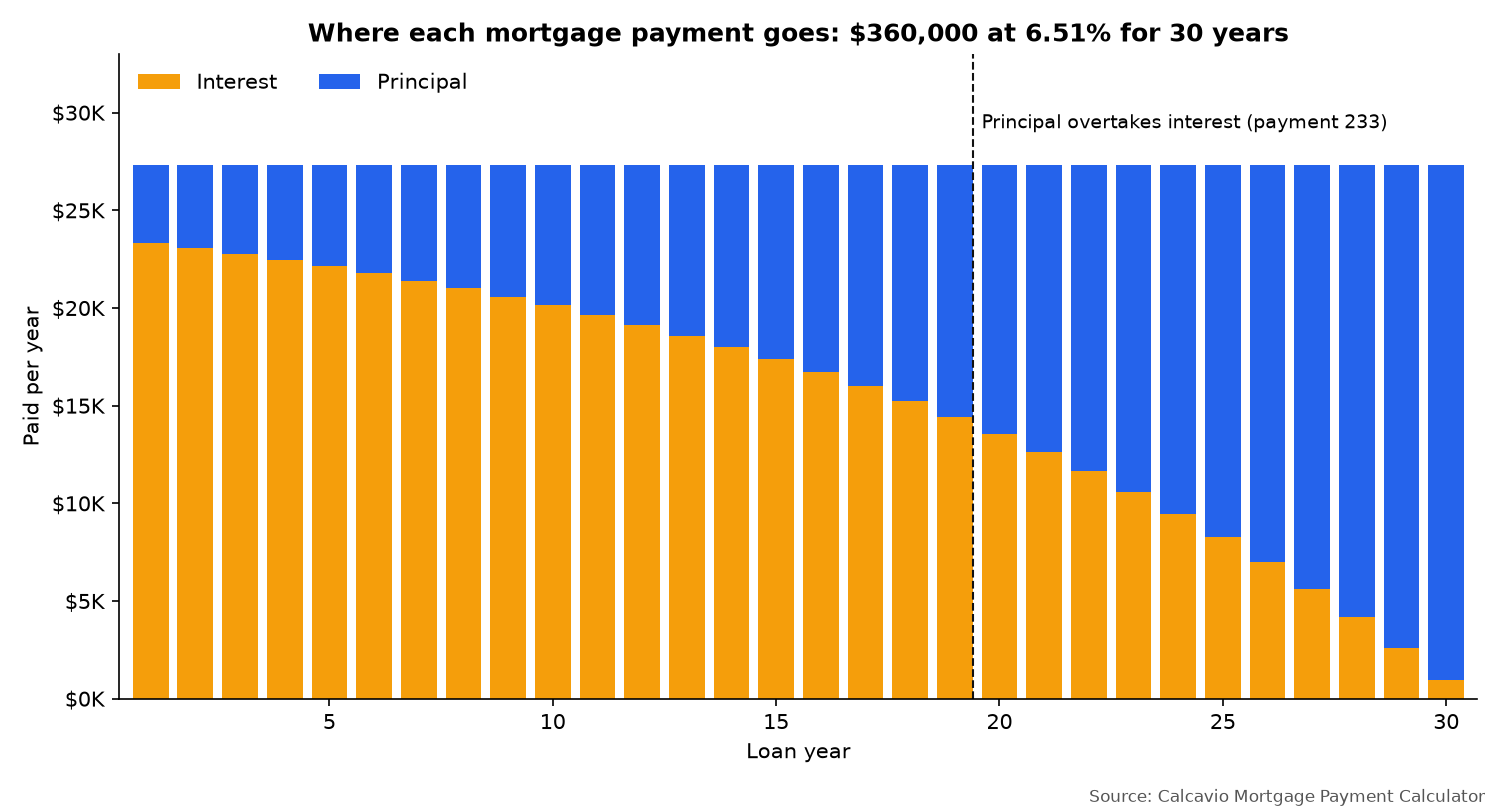
Here's the same $2,277.81 payment at different points in the loan:
| Payment # | Interest | Principal | Balance after |
|---|---|---|---|
| 1 (month 1) | $1,953.00 | $324.81 | $359,675.19 |
| 60 (year 5) | $1,830.86 | $446.96 | $337,038.26 |
| 120 (year 10) | $1,659.45 | $618.37 | $305,270.57 |
| 180 (year 15) | $1,422.30 | $855.51 | $261,319.81 |
| 240 (year 20) | $1,094.21 | $1,183.61 | $200,513.71 |
| 300 (year 25) | $640.29 | $1,637.52 | $116,388.15 |
The takeaway is blunt. After 10 years of payments, you still owe about 85% of the original loan. That's why extra principal early on saves so much.
Question: Maya buys a $320,000 home with 5% down at 7.03% for 30 years. Tax is $5,440 a year, insurance $2,400, and PMI 0.55%. What's her payment, and when does PMI end?
Solution:
Answer: $2,821.31 a month. PMI ends after 11 years 10 months, costing $19,785.33. Requesting removal at 80% ends it after payment 130, a year sooner.
Question: A couple puts 25% down on a $600,000 home. Should they take 15 years at 6.42% or 30 years at 7.03%?
Solution:
Answer: The 15-year loan costs $897.29 more a month but saves $379,016.43 in interest.
Question: Leo buys a $280,000 condo with 10% down at 6.25% for 30 years. Tax is $3,360 a year, insurance $2,160, HOA $350 a month, and PMI 0.55%.
Solution:
Answer: $2,477.11 a month. HOA alone is 14% of the bill, and PMI drops after payment 106.
Question: Priya owes $340,000 at 6.8% for 30 years. What does an extra $250 a month do?
Solution:
Answer: She saves $134,804.75 and finishes 7 years 7 months early. Each extra dollar saves about $2 in interest.
Every example uses the same formula. Rather than working it by hand, plug your numbers into the calculator above.
These are principal-and-interest payments only. Add your taxes, insurance, and PMI in the calculator for the full amount.
| Loan amount | 6.0% | 6.5% | 7.0% |
|---|---|---|---|
| $200,000 | $1,199.10 | $1,264.14 | $1,330.60 |
| $300,000 | $1,798.65 | $1,896.20 | $1,995.91 |
| $400,000 | $2,398.20 | $2,528.27 | $2,661.21 |
| $500,000 | $2,997.75 | $3,160.34 | $3,326.51 |
| $750,000 | $4,496.63 | $4,740.51 | $4,989.77 |
| Loan amount | 5.5% | 6.0% | 6.5% |
|---|---|---|---|
| $200,000 | $1,634.17 | $1,687.71 | $1,742.21 |
| $300,000 | $2,451.25 | $2,531.57 | $2,613.32 |
| $400,000 | $3,268.33 | $3,375.43 | $3,484.43 |
| $500,000 | $4,085.42 | $4,219.28 | $4,355.54 |
| $750,000 | $6,128.13 | $6,328.93 | $6,533.31 |
Here's the principal-and-interest payment at Freddie Mac's September 24, 2026 averages: 7.03% for 30 years and 6.42% for 15 years.
| Loan amount | 30-year at 7.03% | 15-year at 6.42% | 30-year total interest |
|---|---|---|---|
| $250,000 | $1,668.30 | $2,166.79 | $350,586.65 |
| $300,000 | $2,001.96 | $2,600.15 | $420,703.98 |
| $400,000 | $2,669.27 | $3,466.86 | $560,938.64 |
| $500,000 | $3,336.59 | $4,333.58 | $701,173.31 |
| $600,000 | $4,003.91 | $5,200.29 | $841,407.97 |
| $800,000 | $5,338.55 | $6,933.72 | $1,121,877.29 |
| $900,000 | $6,005.87 | $7,800.44 | $1,262,111.95 |
Notice the pattern. On a 30-year loan, every half-point adds roughly $32 to $33 a month per $100,000 borrowed.
A bigger down payment shrinks the loan and can remove PMI entirely. Here's a $400,000 home at 7.03% for 30 years with PMI at 0.55%:
| Down payment | Loan amount | P&I + PMI | Total interest |
|---|---|---|---|
| 3.5% ($14,000) | $386,000 | $2,752.77 | $541,305.79 |
| 5% ($20,000) | $380,000 | $2,709.98 | $532,891.71 |
| 10% ($40,000) | $360,000 | $2,567.35 | $504,844.78 |
| 20% ($80,000) | $320,000 | $2,135.42 (no PMI) | $448,750.92 |
Going from 3.5% to 20% down cuts the monthly payment by $617.35 and saves $92,554.87 in interest. With 10% down, PMI ($165 a month) ends automatically after payment 116.
Each choice shifts your payment differently. Here's how they compare using this page's scenarios.
| Option | Monthly impact | Lifetime impact |
|---|---|---|
| 30-year fixed | Lowest payment | Most interest |
| 15-year fixed | About 30% higher | Less than half the interest |
| Biweekly | Half payment every 2 weeks | $106,093.55 saved on $360K at 6.51% |
| $250 extra a month | +$250 | $134,804.75 saved on $340K at 6.8% |
| PMI removal at 80% | Same payment | Can end about a year before 78% |
Biweekly works because 26 half-payments equal 13 full payments a year. That extra payment goes straight to principal, trimming about 5.8 years off the default loan.
Loan type matters too. Here's how the main US options compare in 2026:
| Loan type | Minimum down payment | Mortgage insurance | Calculator |
|---|---|---|---|
| Conventional | Varies; 20% avoids PMI | PMI below 20% down, removable at 78%–80% | This calculator |
| FHA | 3.5% | FHA mortgage insurance premium (MIP) | FHA Loan Calculator |
| VA | None required by the VA | No PMI; a funding fee may apply | VA Loan Calculator |
| Jumbo | Set by the lender | Varies by lender | Jumbo Loan Calculator |
A loan becomes "jumbo" when it tops the conforming loan limit, which the FHFA set at $832,750 for most of the US in 2026. High-cost areas go up to $1,249,125.
Your home equity is the home's value minus what you still owe. The chart grows the home price by your appreciation rate each year: value in year t = price × (1 + appreciation)^t.
For the default $450,000 home at 3% appreciation, the value reaches $521,673 after 5 years. Meanwhile, the balance falls to $337,038. That leaves about $184,635 in equity, from a $90,000 down payment.
Appreciation isn't guaranteed, though. Home values can stall or fall, so test a lower rate (like 1%) to see a cautious case.
Yes, with a few limits. You can switch the currency, which changes the symbol and number format but doesn't convert amounts. Enter prices in the currency you pick.
The rate cards show averages for the US, UK, Euro area, Australia, and Canada. Only the US 30- and 15-year figures update live from Freddie Mac. The others are national reference figures reviewed by hand, so check your lender's actual quote.
The rate cards show averages for the US, UK, Euro area, Australia, and Canada. Only the US 30- and 15-year figures update live from Freddie Mac. The others are national reference figures reviewed by hand, so check your lender's actual quote.
The calculator covers your recurring monthly cost. It doesn't model these:
Mortgage Discount Points Calculator
Adjustable-Rate Mortgage (ARM) Calculator
Many lenders start with the 28/36 rule. It's a common guideline, not a law: housing costs up to 28% of gross monthly income, and all debt payments, including housing, up to 36%.
On a $100,000 salary ($8,333 a month), that's about $2,333 for housing and $3,000 for all debts. Lenders also look at your debt-to-income ratio (DTI), which the CFPB defines as monthly debt payments divided by gross monthly income.
Here's the income you'd need for a $400,000 house with 20% down at 7.03%:
To test your own income, try the Multi-Rule Home Affordability Calculator.
Multi-Rule Home Affordability Calculator
Your credit score doesn't enter the formula directly, but it changes the rate lenders offer. The CFPB's rate tool shows that borrowers with a 700 score are generally offered lower rates than borrowers with a 625 score on the same loan.
Even half a point adds up. On a $400,000, 30-year loan:
| Rate | Monthly P&I | Total interest |
|---|---|---|
| 6.53% | $2,536.17 | $513,020.86 |
| 7.03% | $2,669.27 | $560,938.64 |
| 7.53% | $2,805.08 | $609,828.67 |
That's a $268.91 monthly gap between 6.53% and 7.53%, and $96,807.81 in interest over 30 years. Check your rate with your lender, then type it into the calculator.
A discount point costs 1% of the loan amount and lowers your rate. The CFPB notes you pay points at closing as part of your closing costs. The question is how long it takes to earn that money back.
The break-even formula is simple: months to break even = cost of points ÷ monthly savings.
Say one point on a $320,000 loan costs $3,200 and lowers your rate from 7.03% to 6.78%. (That cut is an illustration; lenders price points differently.)
If you'll keep the loan longer than 5 years, the point likely pays off. If you might sell or refinance sooner, it probably won't. Run your own quotes in the Mortgage Discount Points Calculator.
Mortgage Discount Points Calculator
You have more levers than just the rate. Here are the main ones, with numbers from this page:
Results are estimates for educational purposes only and are not financial advice. Verify with a qualified professional before making decisions.
Last updated October 2026